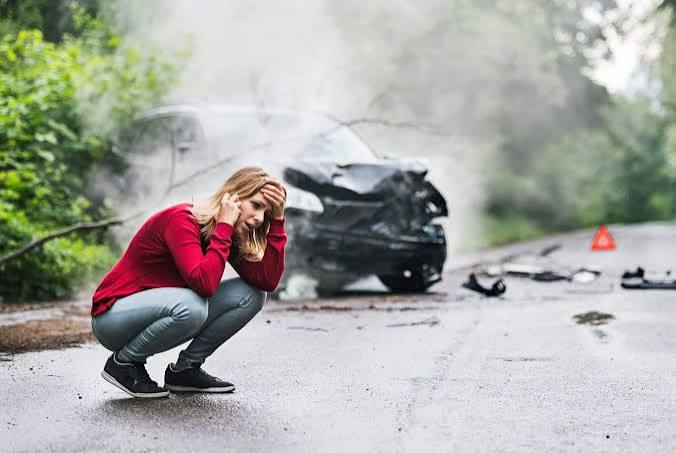
Lending your car to a friend, family member, or colleague may seem harmless, especially when they need help getting somewhere. However, if that person causes an accident while driving your vehicle, the situation can quickly become complicated.
You may wonder whether your car insurance will cover the damage, who will pay for injuries to other people, and whether you could be held legally responsible for the accident.
The answers depend on several factors, including your insurance policy, who was driving, whether you gave permission, and the laws that apply where the accident occurred.
Understanding these issues before lending your vehicle can help you protect your finances and avoid unexpected insurance problems.
1. Does Your Car Insurance Cover Someone Else Driving Your Car?
In some circumstances, your car insurance may cover an accident caused by someone else driving your vehicle with your permission.
However, coverage depends on the policy’s terms and local insurance laws.
Some policies extend certain protections to permitted drivers, while others restrict coverage to named drivers or impose specific conditions on who may operate the vehicle.
For example, if you lend your car to a friend and they accidentally hit another vehicle, your insurance may cover eligible third-party damage if the policy allows that person to drive your car.
However, if the driver is excluded from the policy or does not meet its requirements, coverage could be limited or denied.
Before allowing someone else to drive, check your policy’s rules about permitted drivers, age restrictions, driving licences, and any exclusions.
2. Who Pays for Damage to the Other Vehicle?
When someone causes an accident while driving your car, the cost of damage to another vehicle may be covered by your motor insurance, depending on the type of policy and the circumstances.
Third-party motor insurance generally covers certain liabilities for injury to other people or damage to their property. It usually does not cover damage to your own vehicle.
If you have comprehensive insurance, your policy may provide broader protection, including eligible damage to your car and third-party losses.
For example, if a friend drives your vehicle into another car and is found legally responsible, your insurer may pay for the other vehicle’s eligible repair costs under the applicable liability coverage.
However, the policy limit, deductible, exclusions, and other conditions may affect the amount payable.
If the losses exceed the available insurance limit, the driver or vehicle owner could potentially face additional financial exposure, depending on the applicable law and circumstances.
3. What Happens If Your Own Car Is Damaged?
Damage to your vehicle is handled differently from damage to another person’s property.
If you have comprehensive motor insurance, the policy may cover eligible repairs even when another person was driving, provided the driver and circumstances satisfy the policy requirements.
For example, if someone borrows your car and accidentally crashes into a wall, your insurer may cover the damage to your vehicle after applying any relevant deductible.
However, if you only have third-party insurance, damage to your own car is generally not covered under that policy.
The insurer may also consider whether the driver had permission, was legally licensed, and complied with relevant policy conditions.
Before authorizing expensive repairs, notify your insurer and follow its claims procedure. Take photographs of the damage and retain repair estimates and other relevant documents.
4. Can You Be Held Responsible for an Accident Caused by Another Driver?
The vehicle owner’s potential responsibility depends on the laws governing the accident and the specific circumstances.
In some situations, the driver may be primarily responsible for causing the collision. In others, the owner may also face liability, such as where local law imposes responsibility on the owner or where the owner negligently allowed an unsafe or unqualified person to drive.
For example, knowingly lending a vehicle to someone who is unlicensed or clearly unfit to drive could create additional legal risks.
The fact that your name appears on the vehicle registration does not automatically mean you are responsible for every accident involving the car. However, you should not assume that the driver alone will always bear the consequences.
If the accident involves serious injuries, substantial damage, or a legal dispute, seek advice from a qualified legal professional familiar with the relevant jurisdiction.
5. What If the Driver Was Using Your Car Without Permission?
An accident involving an unauthorized driver can create more complicated insurance and legal questions.
For example, someone might take your keys without permission, or a person you authorized to drive might allow another person to use the vehicle without your consent.
Whether insurance applies depends on the policy wording, the facts, and local law.
Some policies may provide protection in certain unauthorized-use situations, while others may restrict coverage or require specific conditions to be met.
If your car was taken without permission, report the incident to the police where appropriate and notify your insurer promptly.
Provide accurate information about who had access to the vehicle, when it was taken, and what you know about the accident.
Do not assume that an unauthorized driver automatically cancels all coverage or that the insurer must pay every resulting claim.
6. What If the Person Driving Your Car Has No Valid Licence?
Allowing an unlicensed person to drive your vehicle can have serious consequences.
Depending on local law and your policy, the absence of a valid driving licence may affect insurance coverage and could expose the driver or owner to legal penalties.
For example, if you lend your car to someone whose licence has expired or who is not legally authorized to drive, the insurer may investigate whether the policy’s driver requirements were satisfied.
The consequences vary by jurisdiction and policy wording. A licence-related issue does not necessarily produce the same outcome under every insurance contract.
To reduce the risk, verify that anyone borrowing your vehicle holds a valid licence for the relevant vehicle category and is legally permitted to drive.
You should also check whether your insurer imposes additional restrictions on young, inexperienced, or newly licensed drivers.
7. Will Your Insurance Premium Increase After the Accident?
Your insurance premium may increase after an accident involving someone else driving your vehicle, but an increase is not automatic in every case.
Insurers may consider factors such as the cost of the claim, who was legally responsible, your claims history, the policy terms, and their renewal pricing rules.
For example, if your insurer pays a substantial claim after a friend causes an accident in your car, the incident may affect your renewal premium or eligibility for a no-claims discount.
The effect depends on the insurer and the applicable insurance system.
You should ask your insurer how a claim involving another driver could affect your policy, deductible, or renewal terms.
Avoid assuming that lending your car means the accident will have no effect on your insurance simply because you were not behind the wheel.
8. What Should You Do After Someone Crashes Your Car?
If someone causes an accident while driving your vehicle, taking the right steps can help protect everyone involved and support the insurance claim.
Step 1: Check for injuries. Ensure that anyone injured receives appropriate medical attention. Contact emergency services when necessary.
Step 2: Secure the scene. Follow local road safety procedures, move away from immediate danger, and avoid creating additional hazards.
Step 3: Notify the appropriate authorities. Report the accident to the police or relevant authority when required by law or the circumstances.
Step 4: Collect evidence. Where safe and lawful, photograph the vehicles, damage, road conditions, and accident location. Obtain witness details and the other driver’s information.
Step 5: Notify your insurer promptly. Explain who was driving, whether you gave permission, and how the accident occurred. Follow the insurer’s reporting requirements.
Step 6: Keep records. Save police reports, medical documents, repair estimates, receipts, and communications with the insurer.
Step 7: Avoid admitting legal liability prematurely. Cooperate with the relevant authorities and provide accurate facts, but let the insurer and appropriate legal professionals assess responsibility.
Prompt and honest reporting can help prevent misunderstandings and unnecessary claim delays.
9. Can You Recover Money From the Person Who Caused the Accident?
Depending on the circumstances and applicable law, you may be able to seek compensation from the person who caused the accident.
For example, if a friend damages your vehicle while borrowing it and your policy does not cover the loss, you may have grounds to request payment for the repair costs.
If your insurer pays a covered claim, it may also have a right to pursue recovery from a legally responsible party. This process is often called subrogation.
However, the right to recover money depends on the facts, the insurance contract, and local law. An insurer’s recovery action may also affect how much, if anything, you can independently recover for the same loss.
Keep evidence of the damage and any expenses you incur. If a dispute develops, consider obtaining legal advice before agreeing to a settlement or signing documents.
10. How Can You Protect Yourself Before Lending Your Car?
You can reduce the risks of lending your vehicle by taking a few practical precautions.
- Check that the person has a valid driving licence.
- Confirm that your insurance permits them to drive.
- Review restrictions concerning age, experience, and named drivers.
- Make sure the vehicle is roadworthy and properly maintained.
- Explain any important operating requirements or safety concerns.
- Avoid lending the vehicle to anyone who appears impaired, unfit, or unwilling to drive responsibly.
- Keep your insurance and registration documents up to date.
- Consider whether the potential financial consequences justify lending the car.
If you frequently allow other people to drive your vehicle, ask your insurer whether your policy should be updated to reflect that arrangement.
A brief insurance check before handing over the keys can help prevent much larger problems later.
Final Thoughts
When someone drives your car and causes an accident, the outcome depends on the insurance coverage, the driver’s permission and qualifications, the circumstances of the collision, and the laws that apply.
Your insurance may cover certain third-party claims or damage to your own vehicle, but exclusions and coverage limits can affect the result. You may also face legal or financial exposure in some circumstances.
After an accident, prioritize safety, report the incident as required, document the damage, and contact your insurer promptly.
Before lending your car, confirm that the driver is legally permitted to drive and that your insurance provides the protection you expect.