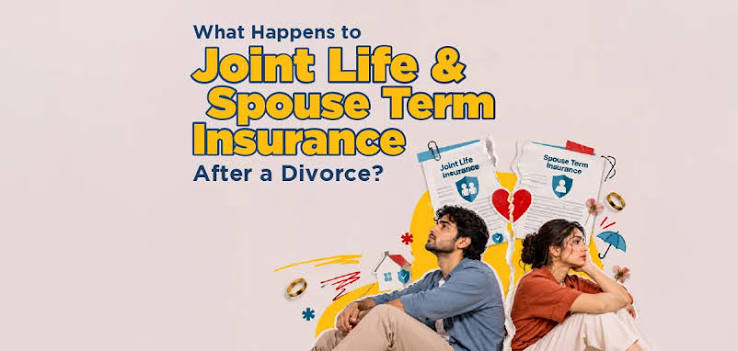
Divorce can affect many aspects of a couple’s financial life, including their insurance arrangements. When two people share an insurance policy, separating their finances and responsibilities can become complicated if they do not understand how the coverage works.
A joint policy may cover a home, vehicle, life insurance benefits, or other shared interests. After a divorce, questions can arise about who owns the policy, who must pay the premiums, who receives benefits, and whether the coverage can continue.
The outcome depends on the type of insurance, the policy terms, the divorce agreement, and the laws that apply. Understanding your options can help you avoid coverage gaps, disputes, and unexpected financial risks during the transition.
1. Does Divorce Automatically Cancel a Joint Insurance Policy?
Not necessarily. Divorce does not automatically cancel every joint insurance policy or remove one former spouse from the contract.
Some policies may continue until they expire, are cancelled, or are changed according to the insurer’s procedures. Others may need to be amended, replaced, or separated because the original arrangement no longer reflects the circumstances of the policyholders.
For example, a couple who jointly insured a home may need to review their coverage when one person moves out or ownership of the property changes.
It is important to contact the insurer rather than assuming that the divorce automatically ends your responsibilities or changes your rights under the policy.
2. What Happens to Joint Life Insurance?
Joint life insurance can be more complicated because the policy may cover two lives under a single contract.
Some joint life policies pay a benefit after the first insured person dies, while others pay after the second insured person dies. The structure determines how the policy operates and what happens to the coverage after a claim.
Following a divorce, the policy may be retained, amended, assigned, or replaced, depending on its terms and whether the insurer permits the requested changes.
For example, if a divorced couple has a joint life policy that pays on the first death, they may need to consider whether continuing that arrangement still meets their financial needs.
Before making changes, ask the insurer whether the policy can be divided into separate policies, whether new underwriting would be required, and whether changing the arrangement would affect the premium or benefits.
Do not cancel an existing policy until you understand the consequences and have considered whether replacement coverage is necessary.
3. Can You Remove Your Former Spouse From a Policy?
Sometimes, but removal is not always as simple as submitting a request.
Whether one person can be removed depends on the insurance product, the policy’s ownership structure, the insurer’s rules, and any applicable legal requirements.
For example, removing a former spouse from a home insurance policy may require evidence that ownership or responsibility for the property has changed.
With life insurance, the policy owner, insured person, and beneficiary may be different individuals. Removing a former spouse from one role does not necessarily remove them from every other role.
Contact the insurer to establish who owns the policy, who is insured, who is named as a beneficiary, and which changes are permitted.
If both former spouses have contractual rights under the policy, the insurer may require additional consent or documentation.
4. What Happens to Joint Home Insurance After Divorce?
Home insurance requires particular attention when a couple separates.
If one former spouse keeps the home, the insurance policy may need to be updated to reflect the new ownership, occupancy, and financial arrangements.
For example, if one spouse moves out and the other becomes the sole owner, the insurer may require the policy to be amended or replaced. A mortgage lender may also have requirements concerning who is insured and how the property must be protected.
If the property is sold, the existing policy may need to be cancelled or otherwise adjusted, while the buyer arranges appropriate coverage.
Do not assume that transferring ownership automatically updates the insurance policy. Contact the insurer before or as soon as the property arrangements change, and confirm the effective date of any amendment.
Maintaining suitable coverage during the transition can help protect the property against risks such as fire, storms, and other insured losses.
5. What Happens to Joint Car Insurance?
Divorce can also affect motor insurance when both spouses are named on a policy or share ownership of a vehicle.
If one former spouse keeps the car, the insurer may need to update the policy to reflect the vehicle’s ownership, main driver, address, and intended use.
In some cases, the remaining owner may be able to continue with an amended policy. In others, a separate policy may be necessary.
If the former spouses own different vehicles, separating the policies may make it easier to manage premiums, claims, and future renewals independently.
Check whether removing a driver or changing the policyholder affects the premium or coverage. Do not assume that a former spouse remains insured to drive the vehicle simply because they were previously listed on the joint policy.
Before the existing arrangement ends, confirm that each vehicle has the required valid insurance.
6. Who Must Pay the Premiums After Divorce?
Responsibility for insurance premiums depends on the policy, any agreement between the former spouses, and applicable law.
A divorce settlement may require one person to maintain specific coverage or pay premiums for a particular period. However, such an agreement does not necessarily change the insurer’s contractual rights automatically.
For example, if both former spouses remain policyholders, the insurer may continue to treat both as responsible for obligations under the contract, depending on its terms.
If one person agrees to pay the premiums but fails to do so, the policy could be at risk of lapsing.
Contact the insurer to clarify who remains responsible for payment and what steps are needed to change the arrangement. Keep written records of any agreed changes.
7. Can Your Former Spouse Still Receive Insurance Benefits?
Possibly. Divorce does not automatically remove a former spouse from every insurance beneficiary designation in every jurisdiction.
The result depends on the policy terms, ownership arrangements, local law, and any relevant court orders or divorce agreements.
For example, a former spouse may remain listed as the beneficiary of a life insurance policy even after the divorce. Whether that designation remains effective depends on the circumstances and applicable legal rules.
Some divorce agreements or court orders may also require a person to maintain life insurance for the benefit of a former spouse or children.
Review your beneficiary designations and obtain legal advice if you are unsure whether a change is permitted. Do not assume that changing your will automatically changes the beneficiary recorded with the insurer.
8. What About Health Insurance for a Former Spouse and Children?
Health insurance arrangements may change significantly after divorce.
Whether a former spouse can remain covered under an existing plan depends on the insurer’s eligibility rules, the type of plan, and applicable law.
In some situations, a former spouse may need to obtain separate coverage after the divorce. Employer-sponsored plans and other group arrangements may have specific rules about when a former spouse ceases to qualify as a dependent.
Children may remain eligible for coverage under one or both parents’ plans, depending on the policy and applicable rules. A divorce agreement or court order may also address responsibility for health insurance costs.
Contact the insurer or plan administrator before making changes. Confirm the date any existing coverage ends and arrange replacement coverage where necessary to avoid a gap.
9. How to Manage Insurance During the Divorce Process
Taking a few practical steps can make the transition easier.
- List all shared policies: Include life, health, motor, home, and other relevant insurance.
- Review policy documents: Identify policyholders, insured persons, beneficiaries, payment obligations, and cancellation rules.
- Contact each insurer: Ask which changes are permitted and what documents are required.
- Coordinate with your legal adviser: Ensure proposed changes are consistent with any divorce agreement or court order.
- Avoid unnecessary cancellation: Confirm replacement coverage before ending an existing policy.
- Keep written confirmation: Save records of amendments, cancellations, beneficiary changes, and premium arrangements.
If a policy covers a substantial asset or provides important financial protection for children, consider obtaining professional advice before making significant changes.
10. Common Insurance Mistakes to Avoid After Divorce
Several mistakes can create unnecessary financial problems after a separation.
Assuming divorce automatically changes a policy: Contact the insurer to confirm what needs to be updated.
Cancelling coverage too early: Ending a policy before replacement coverage begins can leave you exposed to financial losses.
Forgetting beneficiary designations: Review them separately from your will and divorce paperwork.
Ignoring payment obligations: Make sure premiums are paid while the policy remains active.
Overlooking children’s coverage: Confirm who is responsible for maintaining any required protection.
Failing to update personal details: Addresses, drivers, property ownership, and other relevant information may need to change.
Careful planning can help both former spouses understand their responsibilities and maintain appropriate protection.
Final Thoughts
Divorce can change the circumstances under which a joint insurance policy was originally purchased, but the policy does not necessarily end or change automatically.
The next steps depend on the type of insurance, who owns the policy, who is insured, and what the divorce agreement and applicable law require.
Review every shared policy, contact the insurer, clarify payment responsibilities, and confirm that any replacement coverage begins before existing protection ends.
The goal is to ensure that both former spouses understand their insurance obligations and that important financial protection remains in place during and after the separation.