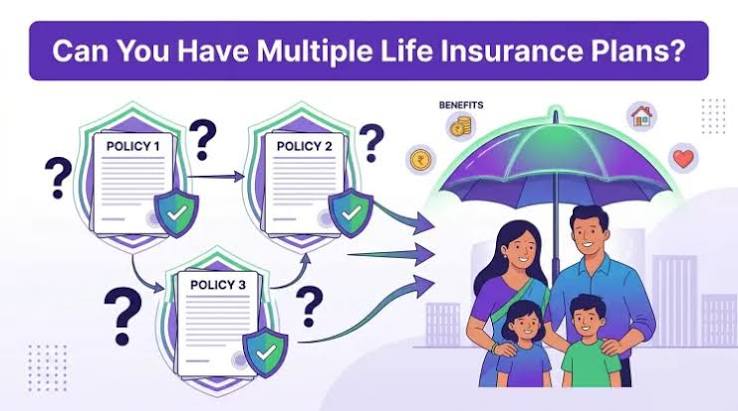
Life insurance can provide financial protection for your family, help cover outstanding debts, and support your loved ones if you pass away. As your income, responsibilities, and financial goals change, you may wonder whether one policy is enough or whether you can purchase life insurance from several different companies.
The good news is that you can generally have life insurance policies from multiple insurance companies at the same time. In many cases, having more than one policy can help you meet different financial needs and provide additional protection for your beneficiaries.
However, owning multiple policies requires careful planning. Insurers may assess your total coverage, affordability, and financial circumstances before approving new applications. Understanding how multiple life insurance policies work can help you avoid unnecessary costs and choose suitable protection.
1. Is It Legal to Have Life Insurance From Multiple Companies?
In many countries, individuals can legally own multiple life insurance policies, including policies issued by different insurance companies.
For example, you might purchase one policy to support your family and another to cover a mortgage or other long-term financial obligation.
Unlike many property insurance policies, life insurance generally does not reimburse a beneficiary only for the financial value of a loss. Instead, each policy usually pays its specified death benefit when the insured person dies and the claim satisfies the policy’s terms.
This means that if you have two valid policies, both may pay their respective benefits to the eligible beneficiaries.
However, insurance laws and application requirements differ by country. You should confirm the applicable rules with licensed insurers in your jurisdiction.
2. How Does Having Multiple Life Insurance Policies Work?
Each life insurance policy is a separate contract with its own premium, coverage amount, exclusions, and conditions.
Suppose you have the following policies:
- Policy A provides a death benefit of $100,000.
- Policy B provides a death benefit of $150,000.
If both policies remain active when you die and both claims meet their respective requirements, your beneficiaries could receive a combined total of $250,000.
The actual payout depends on the policy terms, premium payments, beneficiary arrangements, and applicable laws.
Some policies may also provide additional benefits under specific circumstances, while others may have exclusions or waiting periods that affect certain claims.
Keep copies of all policy documents and make sure your beneficiaries know which insurers to contact when making a claim.
3. Why Would Someone Need Life Insurance From Multiple Companies?
There are several reasons why purchasing multiple life insurance policies may make financial sense.
To increase financial protection
Your existing policy may no longer provide enough coverage after you get married, have children, purchase a home, or take on additional financial responsibilities.
Buying another policy can increase your total protection without necessarily replacing the original contract.
To cover different financial needs
You may want one policy to help support your family over the long term and another to cover a specific financial obligation.
For example, a term life insurance policy could provide protection while your children are financially dependent on you, while another policy could address a longer-term financial goal.
To supplement employer-provided insurance
Some employers provide life insurance as part of their employee benefits. You may decide to purchase an individual policy to supplement that coverage.
This can be particularly useful if your employer’s policy provides less protection than your family may need.
Remember that workplace coverage may end or change when you leave the job, depending on the plan’s terms.
To diversify insurance providers
Some people prefer to hold policies with different insurers rather than depend on a single provider. However, multiple policies can also mean more paperwork, premiums, and renewal responsibilities.
Having policies from different companies does not automatically guarantee better protection, so compare the benefits and costs carefully.
4. Will Insurance Companies Allow You to Have Multiple Policies?
Although multiple life insurance policies are generally permitted, insurers may review your existing coverage before approving a new application.
They want to determine whether the total amount of insurance requested is reasonable in relation to your financial circumstances.
An insurer may consider factors such as:
- Your income and financial obligations.
- The total amount of life insurance you already hold.
- Your age and the coverage period requested.
- The purpose of the additional insurance.
- The insurer’s underwriting rules and other relevant information.
For example, if you already have substantial life insurance coverage, another company may ask why you need an additional policy and whether the requested amount is financially justified.
Approval is not guaranteed simply because you already qualify for insurance elsewhere.
You should answer application questions honestly and disclose existing coverage whenever requested.
5. Can You Claim Benefits From All Your Life Insurance Policies?
In many cases, yes. If you have several valid life insurance policies, each insurer may pay the applicable death benefit when the insured person dies, provided the policy conditions are satisfied.
For example, suppose a person has three policies with death benefits of $50,000, $100,000, and $200,000.
If all three policies are active and the claims are approved, the beneficiaries could receive a combined total of $350,000.
However, beneficiaries must generally submit a separate claim to each insurance company.
They may need to provide documents such as a death certificate, policy details, identification, and claim forms.
Certain circumstances can affect a claim, including inaccurate application information, missed premiums, exclusions, or policy-specific conditions.
It is also important to distinguish individual life insurance from certain employer benefits or specialized policies, which may have different payment arrangements.
6. What Are the Disadvantages of Having Multiple Life Insurance Policies?
Although multiple policies can provide useful protection, they also introduce costs and administrative responsibilities.
Higher total premiums: Every policy has its own premium. Purchasing several policies may place unnecessary pressure on your budget.
More paperwork: You must keep track of different policy documents, payment schedules, insurers, and beneficiary arrangements.
Potential duplication: You might pay for coverage that does not meaningfully improve your financial protection.
Different policy conditions: Each insurer may have different exclusions, claim requirements, and rules for maintaining coverage.
Application complications: Failing to disclose existing coverage when required can create problems during underwriting or a future claim.
Before purchasing another policy, calculate your total premiums and compare the additional benefits with the extra cost.
7. Is It Better to Have One Large Policy or Several Smaller Policies?
Neither option is automatically better. The right choice depends on your financial goals, budget, and need for flexibility.
A single larger policy may be easier to manage because it involves one insurer and one premium schedule.
Multiple smaller policies may provide greater flexibility if you want different coverage periods or separate policies for specific financial responsibilities.
For example, you could choose a long-term policy for family protection and a shorter-term policy to cover a mortgage while the outstanding balance is relatively high.
However, purchasing multiple policies from different insurers may not always be cheaper than buying a single policy with an equivalent total benefit.
Compare the premiums, policy terms, and total cost over the intended coverage period before deciding.
8. How Can You Manage Multiple Life Insurance Policies Effectively?
If you decide to hold life insurance with several companies, use a simple system to keep everything organized.
- Maintain a policy list: Record each insurer’s name, policy number, coverage amount, and contact details.
- Track premium payments: Set reminders or automatic payments where appropriate to reduce the risk of accidental lapses.
- Review beneficiaries: Confirm that your beneficiary designations reflect your current wishes and comply with applicable laws.
- Store documents securely: Keep policy documents and claim instructions in a location your trusted family members can access when needed.
- Review your total coverage: Reassess your insurance after major life events, such as marriage, having children, taking on debt, or retiring.
- Check your budget: Ensure that premiums remain affordable over the long term.
You should also tell your beneficiaries that multiple policies exist so they can contact every relevant insurer when the time comes.
9. What Should You Check Before Buying Another Life Insurance Policy?
Before applying for additional coverage, ask yourself a few important questions.
First, determine how much financial protection your family would need if you were no longer able to provide income. Consider everyday living expenses, education costs, outstanding debts, and other financial commitments.
Next, review your current policies to see whether they already provide sufficient coverage.
Then compare available policies, including their premiums, coverage periods, exclusions, and conditions for keeping the policy active.
Finally, make sure you understand how the new policy fits into your overall financial plan.
A licensed insurance adviser can help you compare options and assess whether additional coverage is appropriate for your circumstances.
Final Thoughts
Having life insurance from multiple companies is generally possible and can be an effective way to increase financial protection, cover different responsibilities, or supplement employer-provided benefits.
Each policy can provide a separate death benefit, provided it remains valid and the claim meets the insurer’s requirements. However, additional coverage also means additional premiums, paperwork, and responsibilities.
Before purchasing another policy, review your existing protection, calculate the total cost, and disclose your current coverage when required.
The goal is not simply to own more life insurance policies, but to secure the right amount of affordable coverage to protect the people who depend on you.